Who Is Responsible for Water Damage in a Condo in Calgary?
Water is coming through your ceiling, and the unit above has a leaking dishwasher. Or maybe a pipe inside the wall has burst, and nobody is quite sure whether it belongs to your unit or the building.
Then the calls start. The property manager gets involved, the condo board has questions, your insurer wants details, and you're trying to figure out something that should have a simple answer: who is responsible for the water damage?
In a Calgary condo, there may be more than one answer. Where the water started matters, but so do the condo bylaws, the damaged property, the corporation's insurance, your own insurance, and the building's standard insurable unit description.
It helps to separate the problem into a few smaller questions instead of trying to decide immediately who should pay for everything.
Start With Where the Water Came From
The first question is usually the easiest one: what caused the loss?
If a common building pipe bursts inside a wall, the condo corporation will generally be involved because corporations are responsible for maintaining and repairing common property.
If the water came from something inside an individual unit, such as a dishwasher, toilet, washing-machine hose, or supply line, the owner is normally responsible for maintaining that item.
Identifying the source gives everyone a starting point. From there, you can work out repair and insurance responsibilities.
Who Repairs the Damage and Who Pays Aren't Always the Same Person
Imagine a dishwasher hose breaks in a fifth-floor unit and water reaches the condo below.
The source is fairly obvious, but the water may have damaged drywall, ceilings, flooring, cabinets, furniture, and parts of the common building structure along the way. Those items don't necessarily fall under the same responsibility.
In Alberta, condominium corporations generally have responsibility for common and managed property. They also carry insurance on the building and on the standard fixtures and finishes they're required to insure inside residential units.
The unit owner's insurance normally fills other gaps, including personal belongings, personal liability, certain improvements or upgrades, and coverage related to the corporation's deductible.
So one leak can involve the corporation, its insurer, one or more unit owners, and their insurers at the same time.
The Standard Insurable Unit Description Helps Draw the Line
One document that becomes very important after condo water damage is the standard insurable unit description, usually shortened to SIUD.
It describes the standard fixtures and finishes the condo corporation insures inside the units. Depending on the building, that can include flooring, wall and ceiling finishes, cabinets, countertops, plumbing fixtures, lighting fixtures, and other original or standard components.
Here's a simple example.
Suppose the standard flooring in your condo is carpet, but you replaced it with upgraded hardwood. If an insured water loss damages the floor, the corporation's responsibility may be based on the standard described in the SIUD. The additional value of your hardwood may fall under the improvements or betterments coverage in your own condo policy.
If you don't know what your building's SIUD says, you can request a copy from the condo corporation or property manager.
What If the Water Started in Your Unit?
This is the part that can catch condo owners off guard.
Under Alberta condo law, if insured damage originates in or from an owner's unit or exclusive possession area, the condominium corporation can potentially recover its insurance deductible from that owner, up to $50,000.
That doesn't always depend on proving the owner was careless.
For example, a supply line could fail while you're away from home. You may have done nothing obviously wrong, but because the damage originated from your unit, the corporation's deductible may still become an issue.
Exceptions include certain construction defects, actions or failures by the corporation or its representatives, and some types of normal structural deterioration.
It's worth knowing how much deductible coverage you have on your own condo insurance policy. Condo corporations can carry substantial water-damage deductibles, and owners shouldn't assume that cost can never reach them.
What Changed With Alberta Condo Chargebacks in 2026?
Alberta introduced new condominium chargeback rules in February 2026.
A chargeback is separate from the corporation's ability to recover an insurance deductible. Where the bylaws allow it, a board may recover certain qualifying costs connected to an owner's, occupant's, or guest's actions or failure to act.
The process is now more formal. The owner must receive notice of the proposed chargeback and have an opportunity to respond. If the board proceeds, it has to approve the chargeback by resolution.
The amount is also limited. Generally, the corporation can charge the lesser of the eligible costs it incurred or the applicable insurance deductible limit, depending on the circumstances.
For most owners dealing with an active leak, the important thing to understand is that a repair bill, an insurance deductible, and a formal chargeback aren't necessarily the same thing.
If you disagree over a significant charge or insurance responsibility, getting advice from your insurer or a lawyer who deals with Alberta condominium law can be worthwhile.
A Few Common Condo Water-Damage Situations
There are always exceptions, but these examples show how different losses can unfold.
These are starting points. The bylaws, SIUD, insurance policies, and cause of the loss determine how a particular claim is handled.
What Should You Do When Water Damage Happens?
When water is actively moving through a condo building, you can wait a little to figure out who gets the final bill. The first job is stopping the damage from spreading.
- Tell the property manager or condo board right away. Water can move into neighbouring units and common areas quickly, so the corporation needs to know.
- Stop the source if you can do it safely. If the problem is a fixture or appliance in your unit, shutting off the water may prevent a much larger loss.
- Take photos and video. Document where you see the water and what's been affected before cleanup changes the area.
- Contact your own insurer. Even when the corporation's policy is involved, your insurer may still need to cover contents, upgrades, additional living expenses, liability, or deductibles.
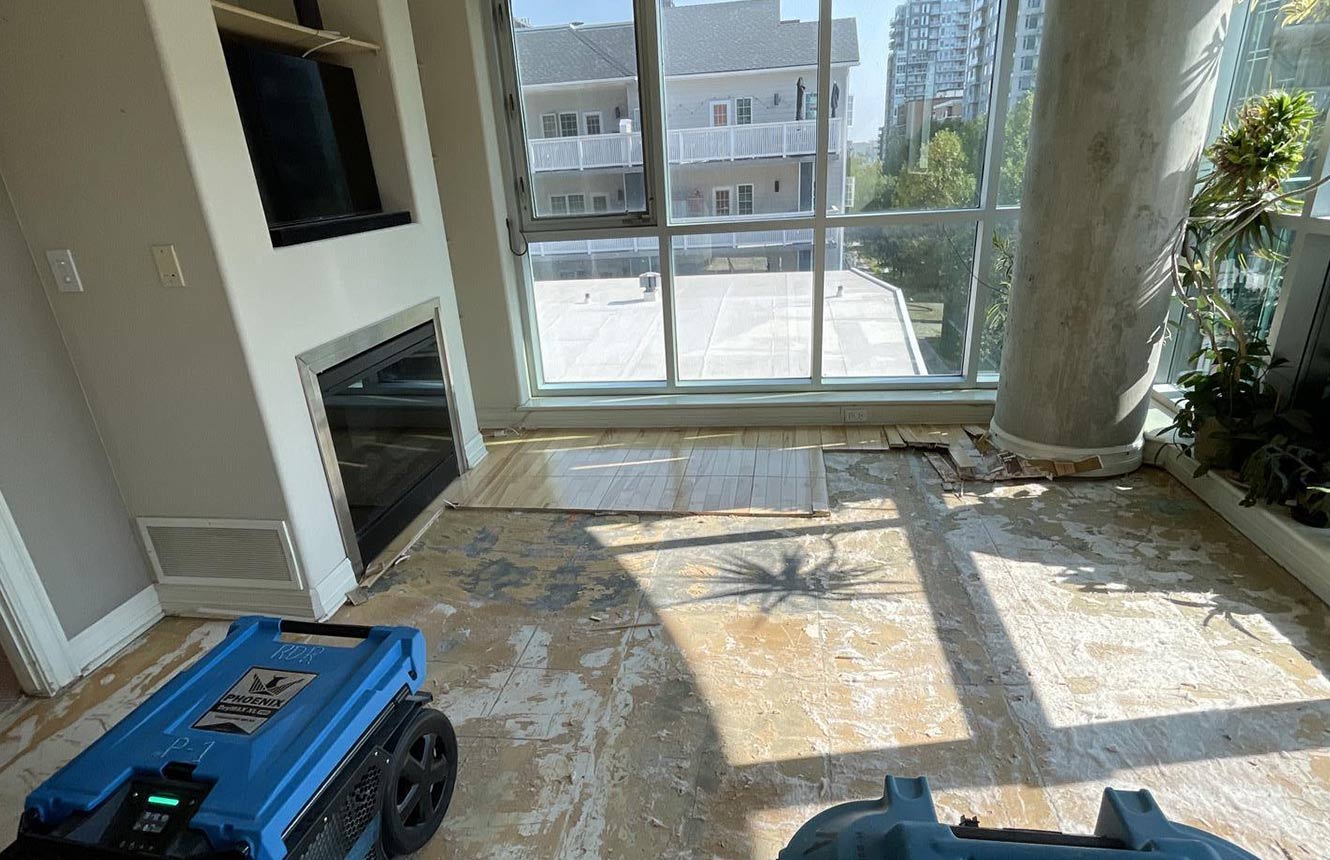
- Get the wet areas inspected and dried. Water can remain inside ceilings, walls, flooring, and insulation after the visible water is gone.
Once the source and extent of the damage are clear, the responsibility discussion becomes much easier.
Which Condo Documents Should You Look At?
If everyone gives you a different answer, check these four documents.
Start with the condo bylaws. They can assign maintenance and repair responsibilities beyond the general rules in Alberta's Condominium Property Act.
Ask for the standard insurable unit description. This shows the standard fixtures and finishes used for the corporation's insurance.
Check the corporation's insurance certificate. Pay particular attention to the current water-damage deductible.
Review your own condo policy. Look at contents, improvements and betterments, personal liability, additional living expenses, and condominium deductible coverage.
You don't have to interpret every clause yourself. Your property manager, insurance broker, adjuster, or lawyer can help with questions that depend on the wording of a specific document.
How Red Dot Restoration Helps With Condo Water Damage
Condo water damage often involves more coordination than a loss in a detached home. Water may travel between units and into areas controlled by both the owner and the condo corporation.
Red Dot Restoration works with condo owners, property managers, boards, and insurance adjusters to assess the affected areas and determine what needs to be dried or removed.
We can handle water extraction, moisture inspection, structural drying, contaminated-water cleanup when needed, documentation, and reconstruction once the area is ready to be repaired.
The clearer the damage is documented from the beginning, the easier it is for everyone involved to understand what happened and move the property toward repair.